The Economics of the Capitalization Table
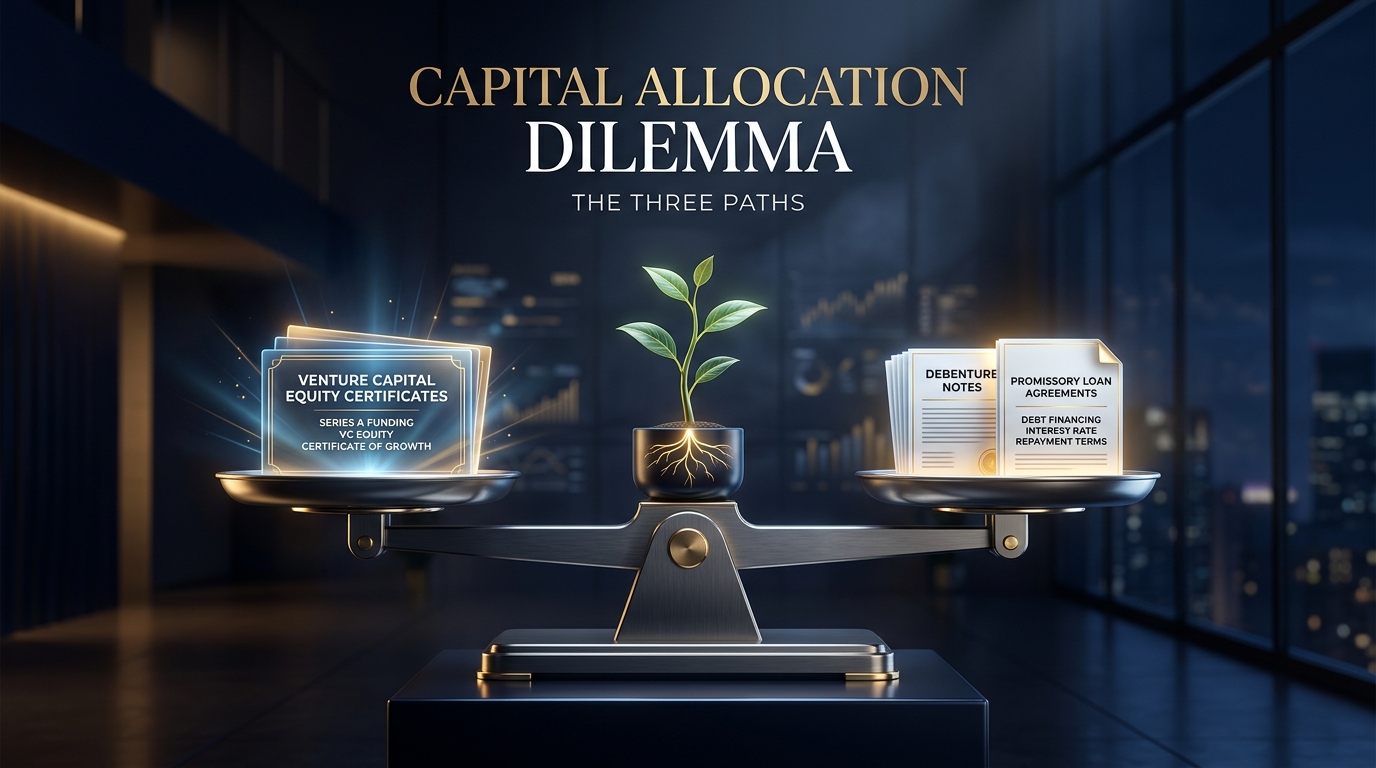
Every commercial enterprise begins as a capitalized liability structure. The choice of capitalization is not merely a funding mechanism; it dictates governance control, return hurdles, bankruptcy priority, and long-term strategic optionality. In corporate finance and business management, we analyze capital allocation through the prism of the Weighted Average Cost of Capital (WACC) and the risk-adjusted cost of capital across three primary funding mechanisms: organic cash flow reinvestment (bootstrapping), non-dilutive commercial debt, and institutional equity.
Founders frequently conflate capital availability with capital efficiency. When venture capital is abundant, operators tend to treat equity as "free money," ignoring the mathematical reality that equity is the single most expensive form of capital a business will ever issue. Conversely, debt is treated with excessive apprehension, despite its tax-deductible interest shield under IRC Section 163(j) and zero equity dilution.
| Financing Vehicle | Cost of Capital | Governance Impact | Cash Flow Burden | Downside Risk |
|---|---|---|---|---|
| Bootstrapping | Opportunity Cost of Capital | 100% Founder Autonomy | Zero External Debt Service | Growth Rate Capped by Cash Velocity |
| Senior Debt / SBA 7(a) | SOFR / Prime + 2–3% (Tax-Advantaged) | Financial Covenants (Zero Board Seats) | Mandatory Amortization & Interest | Default Risk & Personal Guarantees |
| Venture Capital Equity | 30–50%+ Expected IRR Hurdle | Board Seats, Protective Provisions, Liquidation Preferences | Zero Mandatory Debt Service | Severe Dilution & Forced Exit Horizons |
The True Cost of Equity: Mathematical Dilution
To quantify the true economic cost of equity, consider an operator generating $500,000 in annual Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA). To fund a $1,000,000 expansion into new facilities, the operator faces two options: selling a 25% equity stake at a $4,000,000 post-money valuation, or securing an SBA 7(a) term loan amortized over 10 years at a 9.5% interest rate.
Under the debt route, the business incurs an annual debt service of approximately $155,000. Over ten years, total cash interest paid amounts to approximately $550,000. Because interest expense is deductible from taxable corporate income, the effective net cash outflow is substantially lower.
Under the equity route, the founder surrenders 25% of all future residual cash flows and terminal value. If the enterprise scales EBITDA to $3,000,000 over five years and trades at an 8x multiple ($24,000,000 enterprise value), the surrendered 25% stake is worth $6,000,000. The founder effectively paid $6,000,000 in terminal economic value to obtain $1,000,000 in upfront liquidity.
When Debt Outperforms Equity: Asset-Backing & Predictable Unit Economics
Commercial leverage is a financial amplifier. When Return on Invested Capital (ROIC) reliably exceeds the after-tax cost of debt ($ROIC > r_d(1 - t)$), every dollar of borrowed capital enhances Return on Equity (ROE). This is the fundamental engine of private equity and industrial enterprise.
Debt financing is the optimal capital structure under three strict operating conditions:
- Predictable Cash Conversion: Historical receivables and collections exhibit low variance and high predictability ($DSO < 45$ days).
- Defensible Collateral: Real estate, capital equipment, or established accounts receivable provide an asset floor that satisfies lender advance rates.
- Sufficient Coverage Headroom: The pro-forma Debt Service Coverage Ratio ($DSCR$) sits comfortably above 1.35x, providing buffer against unexpected revenue contractions.
The Venture Capital Imperative: Non-Linear Power Laws
Conversely, venture equity is irreplaceable when an enterprise possesses extreme operating leverage and winner-take-most dynamics. If developing the asset requires heavy upfront R&D, multi-year regulatory approvals, or network-effect adoption before generating cash, debt service will strangle the company before it achieves cash break-even.
Venture capital contracts trade ownership for downside protection: if the startup fails, the founder carries zero personal liability to repay equity investors. However, this insurance carries a massive governance price tag: liquidation preferences (often 1x non-participating or participating), anti-dilution ratchets, registration rights, and negative covenants requiring investor consent for major acquisitions, debt issuances, or sales.
Strategic Takeaways for Modern Operators
Prudent business leadership requires matching the tenor and cost of capital to the risk profile of the underlying asset. CapEx and revenue-generating machinery should be financed with equipment debt. Short-term inventory buildup should be financed with revolving lines of credit. High-risk, unproven market experiments should be funded with equity or retained earnings.
Never sell equity to finance an asset that cash flow or commercial credit can comfortably service.
Discussion & Insights (0)
Join the discussion on Career Circle
Sign in or create a free account to post comments, ask questions, and engage with the author.